

Recreational Land Loans
Help Your Clients Discover Their Perfect Outdoor Escape
Owning recreational land is an exciting way for your clients to enjoy the outdoors, whether for hunting, fishing, camping, or simply a private retreat. These types of loans are often difficult to find through traditional wholesale lenders.
Financing recreational land can come with restrictions, but it doesn’t have to be a barrier for your clients. When you partner with United Ag Lending, we specialize in saying “yes” to the recreational property opportunities your clients are passionate about.
A borrower may find the right rural property before they find the right financing. When conventional options don’t fit, our recreational land loans may give lenders another path to explore. United Ag Lending reviews the property’s location, features, and intended use to help determine whether the scenario aligns with an available program.
Our approach makes it simple to offer a tailored recreational land loan that fits your clients’ unique needs and goals.


-
Step: 1
Learn About Their Vision
We begin by connecting with you and your client to understand what type of recreational property they’re looking for and how it fits into their lifestyle.
-
Step: 2
Craft the Right Loan
Based on their goals and property plans, we develop a financing solution that aligns with their needs, giving them the flexibility to move forward confidently.
-
Step: 3
Make It Happen
Once the loan is approved, your client can secure their recreational land and start turning their plans into reality. We stay available as a resource throughout the process to support you and your client.

Recreational Land Loans
Our recreational land loans are a great example of how United Ag Lending reimagines traditional financing. We take the standard idea of a land loan and turn it into a tailored solution that fits your client’s unique vision.
Wholesale lenders often restrict financing for recreational properties. We, on the other hand, focus on providing flexibility so your clients and you, as a partner, have more options to make their outdoor property dreams come true.
Program Aspects:
- Minimum land loan is $500,000
- Minimum of 10 acres, up to 1000s
- Multiple parcels allowed
- Multiple non-contiguous parcels allowed
- Outbuildings, sheds & other land improvements allowed
- Loans for different industries: orchards, vineyards, dairies, ranches, cattle, crops & more
- Purchase, refinance, cash out
- Minimum 680 credit score
- Down payments as low as 30%
- Fixed rates: 10 to 30 years
- Adjustable rates available
- Payment options: monthly, semi-annual, annual
- Can cross collateralize for down payment
- Seller-carried seconds allowed
-
Serving Brokers
 Lenders
Banks
With a recreational land loan from United Ag Lending, you can help your clients explore a variety of possibilities, including:
And this is just the beginning. Our loan keeps your clients’ needs in mind, evolving with them to put their goals within reach.
-
Making an income from their hobby farming
-
Housing up to 50 heads of livestock on the land
-
Owning multiple parcels of land and parcels within reasonable proximity of each other (it’s also possible to combine these properties)
-
Schedule F (Farm) income allowed

Equip Yourself. Impress Your Clients.
Most loan officers don’t have the resources to help clients interested in rural properties. When you team up with us, you can differentiate your services and provide recreational land loans that attract new clients.
If you’re interested in expanding your offerings, here is your chance. Contact us, and we’ll put you in touch with one of our account executives right away.
Recreational Land Lending FAQs
A few property details can shape the financing conversation. These answers can help you identify questions worth addressing before your client gets too far into a purchase.
Before bringing that deal to us, know the property’s acreage, location, current improvements, and how your client plans to use the land. It’s also helpful to know whether the property has road access or utilities and whether the borrower has plans beyond recreation.
With these details in hand we can help you evaluate whether the property and financing request qualify for an available United Ag Lending program.
Zoning and local land-use rules can affect what your client is allowed to do with a rural property. Before purchasing, borrowers should understand whether their intended activities are permitted under the property’s current zoning.
This can be especially important if they plan to add structures, keep livestock, farm part of the acreage, or change how the land is used later.
Yes, some raw or unimproved rural land may be considered, depending on the property and applicable program requirements. Features such as road access, utilities, existing improvements, acreage, and intended use can all help shape the financing conversation.
If a parcel has limited infrastructure or no existing structures, share those details with United Ag Lending early. We can review the scenario and help you understand whether recreational land loans or another available program works best.
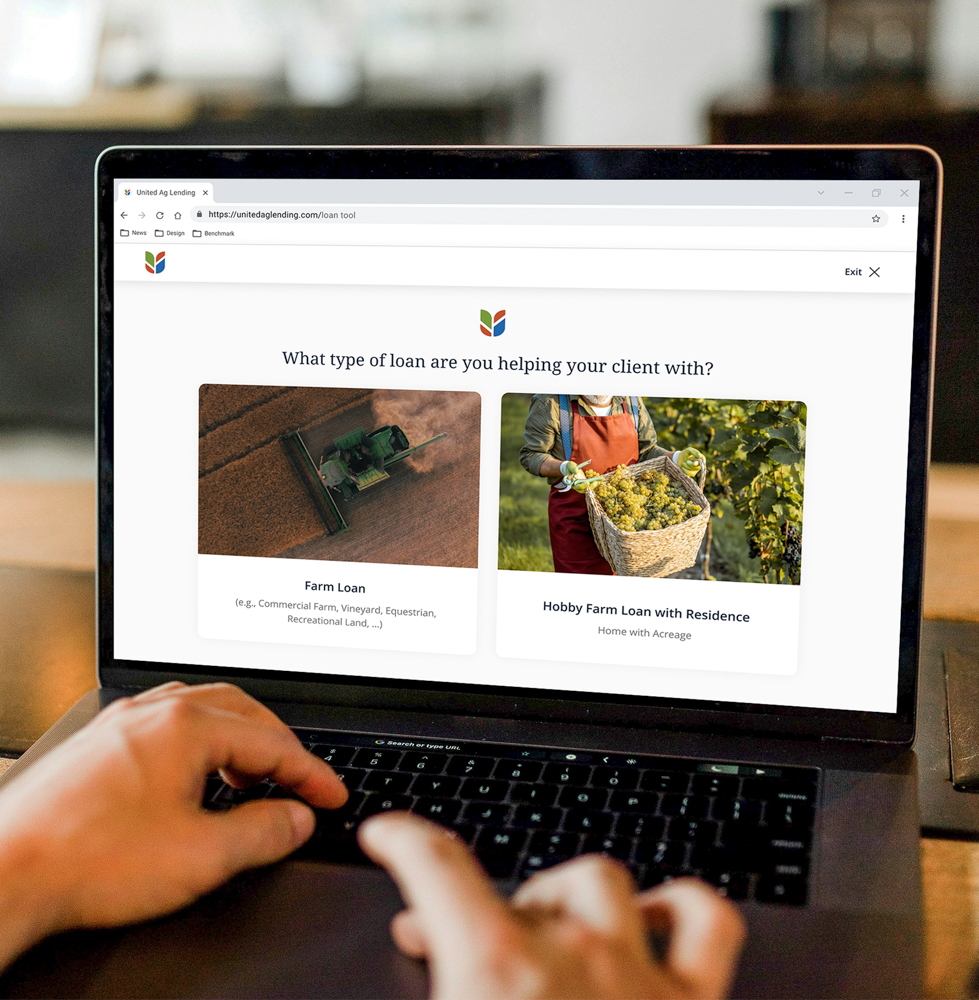
Get Started
The process is quick and easy. Answer a few quick questions, and we’ll determine which loan program is perfect for your clients!