
Hobby Farm Loans
Unite Your Clients With Their Farming Passions
Hobby farming is an exciting way of participating in agriculture on a small scale. These types of loans are not typically available with traditional wholesale lenders.
Unfortunately, there can be financial limitations when applying for a hobby farm loan. This doesn’t have to be the case for your clients. United Ag Lending is in the business of saying “yes” to whatever hobby farm ideas your clients have in mind.
Our hobby farm loans provide lending partners choices for these less conventional scenarios. Together we can find client financing for residential properties with agricultural features or small-scale farming activity. We’ll help you evaluate how your client plans to use the property. We’ll also determine whether our hobby farm program may be a good fit.
Our process makes it easy to develop a customized hobby farm loan based on your client’s unique situation.
-
Step: 1
Consultation
Get the purchasing process started with an introductory conversation to get to know you and your client’s needs.
-
Step: 2
Recommendations
Our loan officers will customize a loan program that fits your client’s property goals.
-
Step: 3
Receive Loan
Once your client receives their loan and moves their plans forward, we remain a trusted resource for you.

Hobby Farm Loans
Our hobby farm loans are a prime example of what we do at United Ag Lending. We take the conventional understanding of what a hobby farm loan is and turn it into a customizable solution.
Typically, wholesale lenders have strict limitations on what you can accomplish with hobby farm loans. However, we find it fulfilling to give your customers and our partners more flexibility.
Program Highlights:
- Minimum of 5 acres
- Home with up to 160 acres (more allowed on a case-by-case basis)
- Ag-exempt properties allowed but not required
- Schedule F (Farm) income allowed
- Purchase, rate/term, and cash-out refinances to pay off debt, home, or land improvements, or cash in hand
- Consolidate land and construction loans into a permanent mortgage loan
- Primary homes or second homes
- Land value can exceed 30% of appraised value (other lenders don’t allow this)
- Dwelling value only required to be 25% of value (lower allowed on a case-by-case basis)
- Multiple parcels allowed and parcels within reasonable proximity of each other (combine properties)
- Farming and farm income allowed, if not sole income
- Horse facility with indoor/outdoor arena and no limitation on horse stables
- 50 heads of livestock or fewer are acceptable
- Shed homes, barndominiums with typical living quarters, log homes, and multiple homes allowed on property
- Fixed 15- and 30-year terms
-
Serving Brokers
 Lenders
Banks
With a hobby farm loan from United AG Lending, you can offer your clients a number of different opportunities, including:
These opportunities are just the start of what we can do with our hobby farm loans. We’ve created them with your customers in mind.
-
Making an income from their hobby farming
-
Housing up to 50 head of livestock on the land
-
Owning multiple parcels of land and parcels within reasonable proximity of each other (it’s also possible to combine these properties)
-
Schedule F (Farm) income allowed

Putting Your Clients First
Your clients have dreams for their hobby farm, and we want them to become a reality. Our hobby farm loans are a key to their success, giving your clients the flexibility and freedom to manage their farm as they would like.
Ready to take the next step? Let’s start a conversation with your AE about our hobby farm loans and find the right solution for your clients.
Hobby Farm Lending FAQs
These answers can help you recognize a potential hobby farm scenario and gather the right information before bringing the deal to United Ag Lending.
The borrower’s relationship to the farming operation is an important distinction. With our hobby farm program, farming can generate income. However, it can’t be the borrower’s sole source of income.
The property must also include an existing home used as a primary or secondary residence. If agriculture is the borrower’s primary business and income source, a commercial agricultural program may be more appropriate.
When approaching scenarios for hobby farm loans, you should know:
- The property’s acreage
- Existing residence
- Your client’s intended use
- Whether they plan to earn farm income
- If the property will serve as a primary or secondary residence
Those details help us understand the scenario before a full file is assembled. If you’re unsure whether the property fits, we can talk through it with you early.
We don’t require your borrower to have prior professional farming experience. The program is intended for clients pursuing small-scale agricultural interests while maintaining another primary source of income.
Qualification still depends on the borrower and on the property meeting applicable program requirements. It’s best to bring us the scenario rather than assuming a first-time hobby farmer won’t qualify.
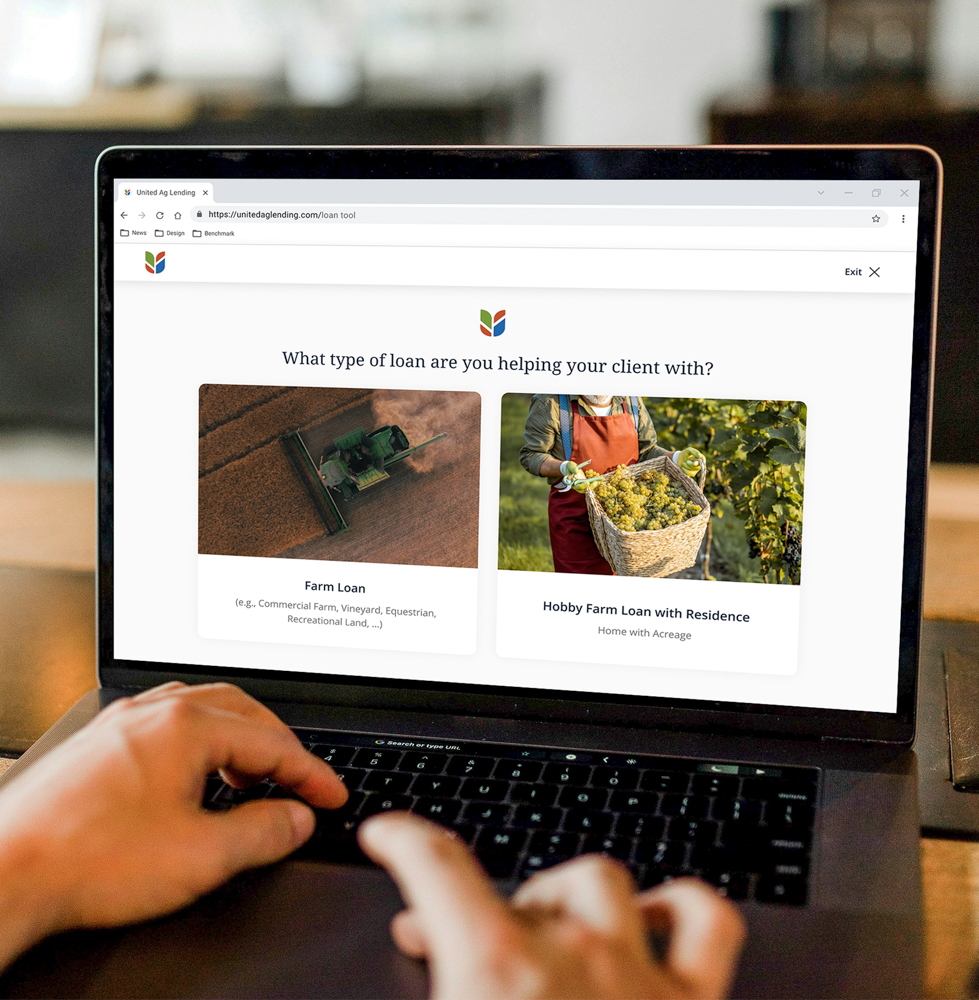
Get Started
The process is quick and easy. Answer a few quick questions and we’ll determine which loan program is perfect for your clients!